Skip to content

Real Estate News

Real Estate News

Housing Costs Strain a Growing Share of Canadian Households

Housing affordability worsened for Canadian households in 2024, with mortgaged homeowners driving much of the increase. Renters remained more likely to face unaffordable housing, while recent movers paid considerably more than longer-term tenants. First-time buyers and households awaiting social and affordable housing also reported substantial financial pressure. #HousingAffordability #RentalMarket #HousingCosts #CanadaHousing

Read more
Real Estate News

Canadian Housing Shows Early Recovery Signs, but Risks Cloud the Outlook

Canada’s housing market is beginning to show signs of recovery as resales rise and prices stabilize. Stronger momentum is expected next year, but the improvement will likely remain gradual and uneven. High condo inventories, limited investor demand and economic uncertainty could still produce another false start. #RealEstate #HousingMarket #CanadaRealEstate #MarketRecovery

Read more
Real Estate News

Canada’s Housing Market Faces a Gradual and Uneven Path to Recovery

Canada’s housing market remains caught between an extended correction and a tentative recovery. Sales and prices are expected to decline in 2026 before improving modestly next year, supported by pent-up demand. Regional progress will be uneven, and condominium markets may continue to lag as economic risks threaten further false starts. #RealEstate #HousingMarket #CanadaRealEstate #MarketRecovery

Read more
Real Estate News

Rental Construction Rises as Canada’s Homeownership Supply Falls Behind

Canada’s housing construction is increasingly shifting toward purpose-built rentals as ownership supply weakens. Toronto’s rental starts are rising sharply, while condominium and ground-oriented development continue to decline. CMHC warns that failing to build enough ownership housing now could create another supply crunch when demand recovers. #HousingSupply #RentalMarket #HousingMarket #CanadaRealEstate

Read more
Real Estate News

Bank of Canada Keeps Rate at 2.25% as Inflation Concerns Increase

The Bank of Canada has kept its overnight rate unchanged at 2.25% as inflation risks increase. Higher oil prices, rising global bond yields and upcoming tariffs are adding uncertainty to the economic outlook. A future rate hike is back on the table, depending on how economic conditions and incoming data develop. #RealEstate #HousingMarket #CanadaRealEstate

Read more
Real Estate News

Toronto’s Fall Housing Market May Gain Momentum as Buyers Stay Cautious

Toronto’s housing market could see more activity this fall following a relatively quiet summer. Bidding wars are reappearing in parts of the market, while fewer listings could create greater competition. Buyers remain cautious amid economic uncertainty, and the condo segment may continue to struggle. #TorontoRealEstate #HousingMarket #GTARealEstate #CanadaRealEstate

Read more
Real Estate News

Canadian Home Sales Edge Higher as Market Balance Improves

Canadian home sales recorded a fourth consecutive monthly gain in July, while new listings declined again. Supply and demand continued moving toward a more balanced market across much of the country. Prices remained broadly stable, with the national MLS® Home Price Index posting its first monthly increase since November 2024. #RealEstate #HousingMarket #CanadaRealEstate

Read more
Real Estate News

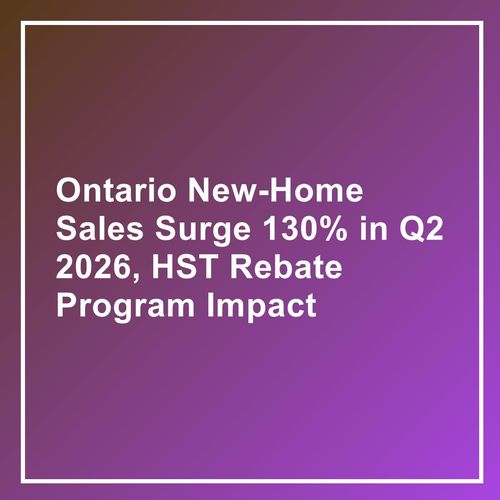
Buying a New Home in Ontario? How GST/HST Relief Could Save First-Time Buyer Thousands

Eligible first-time buyers of newly built or substantially renovated homes priced up to $1 million can recover the full 5% federal GST and, for purchase agreements signed between April 1, 2026, and March 31, 2027, the full 8% Ontario HST, totaling up to $130,000 in tax savings (with rebates phasing out on homes priced at $1 million–$1.5 million), provided they meet strict purchase agreement, occupancy, and construction timeline requirements, making buying new especially attractive in Ontario.

Read more
Real Estate News

First-Time Homebuyers’ Down Payment Guide

Canada’s minimum down payment for first-time buyers is 5% on the first $500,000 of the purchase price; on the portion from $500,000 to $999,999 it rises to 10%, and remains 10% for homes priced between $1,000,000 and $1,499,999, reflecting the CMHC-insurable cap increase to $1.5 million. For properties at or above $1.5 million, a minimum 20% down payment is required. Moreover, eligible first-time buyers purchasing new builds with insured mortgages can access a 30-year amortization instead of the standard 25-year term, reducing monthly payments and improving affordability.

Read more
Real Estate News

What Does a First-Time Homebuyer Need to Know About Ontario's Mortgage Stress Test? How Does It Work?

While many homebuyers assume banks set the stress-test rate, it actually stems from a standardized formula mandated by the Office of the Superintendent of Financial Institutions (OSFI). This regulatory framework ensures that lenders across Canada apply a consistent qualifying rate—currently the greater of the Bank of Canada’s five-year benchmark rate or the lender’s contractual mortgage rate plus 2%—to assess a borrower’s ability to handle potential interest rate increases. By implementing this uniform approach, OSFI aims to safeguard individual and systemic financial stability, providing both borrowers and institutions with clear, predictable criteria.

Read more
Real Estate News

What’s the Best Way for First-Time Homebuyers to Handle Inspections, Financing, and Legal Reviews During the Conditional Period?

During the conditional period of an Agreement of Purchase and Sale, first-time buyers secure critical safeguards by setting specific conditions, typically a satisfactory home inspection, confirmed mortgage approval, and a legal review of title and documents, each with its own deadline. Begin by booking a licensed home inspector immediately after the offer is accepted, ensuring any hidden defects are uncovered before you’re bound to proceed. At the same time, stay in close contact with your mortgage specialist, providing all required documentation and responding promptly to inquiries so financing approval arrives well before the condition expiry. Finally, engage a real estate lawyer to examine the agreement, title, property taxes, and any encumbrances, asking questions about anything unclear and requesting amendments if necessary. By managing these tasks methodically and following the timeline in your agreement, you maintain control and minimize risk, giving you confidence to remove conditions and move forward with your first home purchase.

Read more
Real Estate News

What Does a First-Time Homebuyer Need to Know About mortgage approval, pre-approval, and Pre-Qualification? 

Pre-qualification, pre-approval, and final mortgage approval each mark distinct stages in the home-buying financing process: Pre-qualification offers a preliminary estimate of borrowing capacity based on self-reported financial information, often without a credit check; pre-approval carries greater weight, involving a lender’s review of credit reports, income documentation, and debt obligations to issue a conditional commitment; and full approval, granted only after underwriting review, property appraisal, and verification of all financial details—represents the lender’s definitive commitment to fund the mortgage. These steps help buyers understand their budget, strengthen offers, and ensure a smooth closing.

Read more

The Rise of Co-Mortgaging in Canada: A New Trend in Real Estate Financing.

Co-mortgaging, a growing trend in the Canadian real estate market, is the focus of this blogpost. As more individuals seek innovative ways to enter the housing market, co-mortgaging offers a solution by allowing multiple parties to share the financial responsibility of a mortgage. This article explores the benefits and considerations of co-mortgaging, highlighting its potential to increase home affordability and foster financial partnerships. With an emphasis on professionalism, we delve into the intricacies of this emerging trend, providing valuable insights for both buyers and sellers navigating the co-mortgaging landscape in Canada.

Read more